Author: Joseph Anderson

  • Business Acumen: The 9 Human Efficiency Losses

    Business Acumen: The 9 Human Efficiency Losses

    The equipment losses are about how the machines run. These are about how the people work. Same waterfall, completely different fix. 

    If the 11 equipment losses are where reliability work pays off, the 9 human efficiency losses are where it doesn’t. That’s the single most important thing to understand about this category: these losses mirror the equipment ones, but you don’t solve them with maintenance. You solve them with planning, organization, training, and better physical layout. Throw a reliability program at a planning problem and you’ll spend money fixing machines that were never the issue. 

    These nine split into three scheduled labor losses and six others. 

    The three scheduled labor losses 

    These are the labor side of your planned downtime. The equipment was supposed to be down; the question is whether the people were used well while it was. 

    1. Scheduled Maintenance Labor Losses. Maintenance labor sitting idle during planned windows. If your wrench-time during scheduled work is 35%, then two-thirds of your maintenance labor is non-productive even on a good, planned day. 
    1. Scheduled Engineering Labor Losses. Engineering labor wasted during planned project windows, usually from scope creep, unclear handoffs, or late parts and drawings. Engineering hours are among the most expensive in the plant, so wasting them hits your project capital costs directly. 
    1. Scheduled Operations Labor Losses. Operations labor lost during planned operations windows. Ten people standing around for a 15-minute handoff briefing is a real, recurring loss, every shift, forever. 

    The six other human efficiency losses 

    1. Management and Planning Losses. Wait time caused by poor planning of the work itself: waiting for materials, tools, instructions, permits, or for equipment to be released. This is the single biggest source of lost wrench-time in maintenance, and it’s almost always a symptom of a reactive culture rather than lazy people. 
    1. Operating Motion Losses. Inefficiency in how operators have to move: bending, stretching, walking to fetch parts, hunting for tools. The hidden cost here isn’t just slower work; it’s injury risk. Every workers-comp incident is six figures of direct cost plus the productivity and morale damage around it. 
    1. Line Organization Losses. Inefficiency from how the line is laid out and how the workload is balanced across stations. It shows up as the same operators always being overloaded while others sit idle, or as bottlenecks nobody can quite explain. 
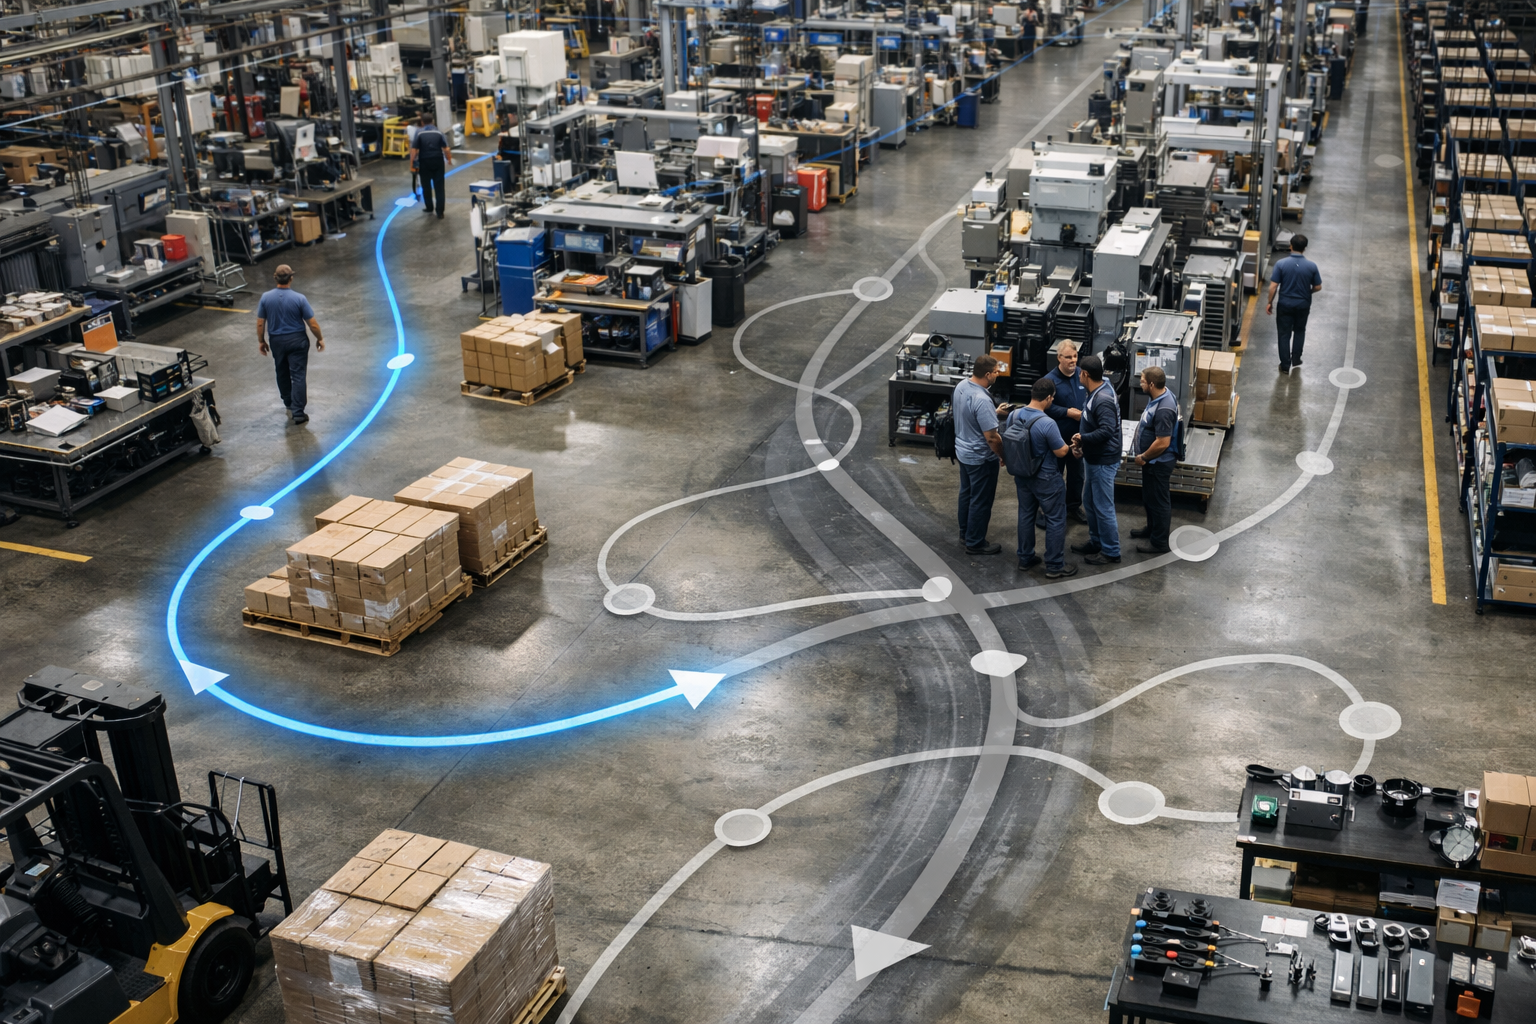
    1. Logistics Losses. Time lost moving material around the plant: operators walking for parts, dollies waiting on forklifts, work backing up because the next station can’t accept it. A finished pallet that sits 20 minutes waiting for a forklift is 20 minutes of unnecessary tied-up product, plus a safety hazard. 
    1. Waiting Losses. Operators waiting on equipment, materials, instructions, or each other. Easy to spot, hard to act on. This is one of the most demoralizing losses there is, because idle time tells your people that nobody values their time. 
    1. Setup and Adjustment Labor Losses. The labor side of equipment setup and adjustment, where skilled people are tied up redoing work that should have been right the first time. It’s a doubled cost: the equipment is down, and high-skill labor is being burned on something that was preventable. 

    Real-world example: wrench-time on a reactive shift. A maintenance supervisor films a typical shift. Out of eight paid hours per technician: 

    • Actual wrench time on equipment: 2.1 hours. 
    • Walking to and from the parts crib: 1.4 hours. 
    • Looking for tools: 0.9 hours. 
    • Waiting for permits or for production to release equipment: 1.1 hours. 
    • Waiting for instructions or supervisor decisions: 0.6 hours. 
    • Breaks, meetings, and paperwork: 1.9 hours. 

    Wrench-time comes out to 26%. With proper planning and kitting, world-class crews hit 55% to 60%. Closing that gap means doing roughly twice the work with the same headcount. That, in one shift, is a Management and Planning Loss you can see and size. 

    Wrench-time is the canary 

    If you want one number that tells you whether your plant has a human efficiency problem, it’s wrench-time: the share of paid maintenance hours actually spent turning wrenches on equipment. A reactive plant runs around 25% to 35%. A well-planned plant runs 55% to 65%. That gap isn’t about working harder. It’s about whether the work was set up so people could do it. 

    Try it yourself 

    Pick one of these to put a rough dollar value on this week: 

    • Time spent waiting for parts across your last five work orders. 
    • Distance an operator walks on your busiest line in a single shift, roughly estimated. 
    • The number of times someone had to stop and ask a supervisor for a decision before they could keep working. 

    Each of these is a number, and each number has a cost. Try to attach one. 

    Key takeaways 

    • Human efficiency losses mirror the equipment losses, but the fix is planning, organization, and training, not maintenance. 
    • Wrench-time is the canary: a reactive plant runs 25% to 35%, a planned plant 55% to 65%. 
    • Operating motion and line organization losses are large but invisible. They surface as fatigue, injuries, and bottlenecks. 
    • Waiting losses crush morale. Fix them and engagement rises right alongside productivity. 


    Coming next, Part 2, Post 4: The 10 Resource Losses.

    If you want to understand where your labor hours are slipping away, start with one number this week. Measure it. Put a dollar value on it. When you can see the loss, you can recover it. If you want help quantifying these losses inside your plant, reach out and we will walk you through the first assessment.
  • Business Acumen: The 11 Equipment Losses

    Business Acumen: The 11 Equipment Losses

    The 11 Equipment Losses 

    The machines are talking. Most plants only hear the loudest one. 

    In the last post we named the three families of loss. Now we go into the first and most familiar one: the 11 ways your equipment quietly hands money back. Familiar is the trap here. Most plants chase the loud, visible losses and walk right past the bigger, quieter ones. By the end of this post you’ll know all eleven by name, and you’ll know which ones are probably costing you the most. 

    The 11 equipment losses split into two groups: four are scheduled, and seven are unplanned. Both cost money. The scheduled ones are necessary, but necessary is not the same as efficient. 

    The four scheduled losses 

    These are the planned reasons you take a line down. You can’t eliminate them, but you can absolutely tighten them. 

    1. Scheduled Maintenance Time. Planned downtime for PMs, lubrication routes, inspections, and calibrations. The loss isn’t the PM; it’s the slop around it. A four-hour PM that runs six because parts weren’t staged just bled you two hours for nothing. 
    1. Scheduled Engineering Time. Planned downtime for installs, upgrades, and line modifications. A poorly scoped install that creeps from two days to five delays your return to production and burns labor the whole time. 
    1. Scheduled Operations Time. Planned downtime for inventory counts, training, cleanings, and audits. Stretching a two-hour training into a lost six-hour shift because nothing else was organized around it is pure waste. 
    1. Lack of Demand. The line isn’t scheduled because there are no orders. That’s not the plant’s fault, but the fixed-cost meter still runs during idle hours. Using that time well, for extra PMs, training, or projects, is the plant’s opportunity. 

    Real-world example: the PM that ran long. A four-hour planned PM on a packaging line took seven hours. The wrong gasket was kitted, costing 30 minutes to source the right one. Two technicians showed up without the right calibration tool, costing 45 minutes. Startup defects after restart threw away 90 minutes of product. The PM itself was fine. The planning around it was not. That extra three hours cost about $9,000 in lost contribution, and a 30-minute pre-PM kitting check would have prevented most of it. 

    The seven big losses 

    These are the seven unplanned losses you have the most control over, and they’re the ones that move OEE the most. This is where most reliability programs focus, and rightly so. 

    1. Setup and Adjustments. Deviation from a set standard of time. For example, a scheduled 30-minute changeover takes 45 minutes. The 15 minutes that was unplanned cost you units, equating to profit lost.  
    1. Breakdowns. Unplanned stops of 10 minutes or more that need a part to fix. This is the most visible loss, which is exactly why it gets too much of the attention. A single major breakdown can wipe out a week of contribution margin on a critical line. 
    1. Process Failures. Unplanned stops of 10 minutes or more that do not need a part: sensor faults, software glitches, control logic, operator confusion. These get missed because they don’t look like classic breakdowns, but they burn just as much time and often force a quality check on whatever ran before the stop. 
    1. Speed Losses. The gap between design speed and actual run speed. This is the most insidious loss in the building. A line built for 100 units a minute that runs at 80 has lost 20% of its capacity, and not one minute of it shows up on a downtime sheet. 
    1. Minor Stops. Stops under 10 minutes. Death by a thousand cuts. Two hundred short stops of three minutes each add up to 10 hours of downtime a week, invisible on the dashboard because no single event is big enough to notice. 
    1. Startup Defects. Defective product made during warm-up after a stop or changeover. Most plants accept this as “just how it is.” It isn’t. Reducing startup waste is one of the highest-return quality plays available. 
    1. In-Process Defects. Defective product made during normal running. This is a direct hit to material and labor cost, because a defective unit carries the full cost of being produced and generates exactly zero revenue. 

    Real-world example: the minor stops nobody sees. On a frozen-meal packaging line, the operator hits reset about 100 times a shift to clear minor jams from a tray feeder. Each reset takes 90 seconds. That’s 150 minutes per shift, two and a half hours of downtime, every shift, never logged because each event is under 10 minutes. At $4,200 an hour in lost contribution, that’s $10,500 per shift, or about $7.5M a year across three shifts. The fix was a $14,000 redesign of the tray-feed transfer. Payback: less than one day. 

    Read those two examples back-to-back and you can see the lesson. The loud loss, the breakdown, gets a war room. The quiet loss, 90 seconds at a time, gets a $7.5M annual bill and no attention at all. 

    Try it yourself 

    Walk one of your lines for 30 minutes during normal running. Tally three things: 

    • Every time the line stops or hesitates. 
    • Whether each stop was over or under 10 minutes. 
    • Whether anyone wrote it down. 

    Then ask how much of what you just watched is actually making it into your reported OEE. The gap between what you saw and what got recorded is your minor-stops opportunity, and it’s usually a lot bigger than anyone expects. 

    Key takeaways 

    • Equipment losses split into 4 scheduled and 7 unplanned. The 7 unplanned are the ones that move OEE. 
    • Speed losses and minor stops are the most under-counted, and often the largest. 
    • Most plants over-focus on breakdowns because they’re visible. The bigger money usually hides in minor stops, speed, and quality losses. 
    • If you can’t tell a Process Failure from a Breakdown, you can’t match the right strategy to the loss. 


    Coming next, Part 2, Post 3: The 9 Human Efficiency Losses. 

  • Business Acumen: Where the Money Hides

    Business Acumen: Where the Money Hides

    Where the Money Hides 

    Profit is not won by big swings. It’s won by spotting the leaks that drain it every day. 

    The 30 Losses Framework 

    Walk into your plant tomorrow and ask one question: “Where are we losing money?” You’ll get a different answer from every department. Operations will say breakdowns. Maintenance will say bad operating practices. Engineering will say poor design. Finance will say overspending. 

    Here’s the thing. They’re all right. They’re each describing one part of the same elephant. What they’re missing is a single map that names every part at once, so the plant can stop arguing about whose answer is correct and start working the whole animal. 

    That map is the 30 Losses framework. 

    The idea, in plain English 

    The 30 Major Losses are the 30 buckets where time, effort, and material slip away in a manufacturing facility. If you know which bucket your loss is in, you know where to go to get it back. 

    That’s the whole value of naming things. A vague sense that “we’re leaving money on the table” funds nothing. “We have a speed loss bucket worth $40,000 a month on Line 3” funds a project. The framework turns a feeling into a target. 

    Three families of loss 

    The 30 losses sort into three families: 

    • 11 Equipment Losses. Time and capacity lost on the machines themselves. 
    • 9 Human Efficiency Losses. Time and effort lost in how people work. 
    • 10 Resource Losses. Money lost in materials, energy, and inventory. 

    This split does real work for you. Together these categories tell you whether your problem is a machine problem, a people problem, or a resource problem; and that distinction decides where you should spend your improvement dollars. Pouring maintenance budget at what is actually a materials problem is how plants stay busy and broke at the same time. 

    How the losses stack up 

    Picture a waterfall. You start at the top with all the hours theoretically available to a machine, 168 hours in a week, and you chip away. 

    • First you subtract scheduled downtime, the time you planned not to run. 
    • Then you subtract the unplanned losses, the breakdowns and stops. 
    • Then you subtract speed losses, the gap between design pace and actual pace. 
    • Then you subtract quality losses, the output you made but couldn’t sell. 

    Whatever survives at the bottom is your real productive output. The same waterfall logic applies to people and to resources. Every loss bucket is just a place where water leaks out on the way down. 

    The three roll-ups that score it 

    Three terms summarize how badly the 30 losses are bleeding you. We’ll calculate each one in Part 3; for now, just learn what they mean. 

    Metric  What it measures  Goal 
    Loading  How much of available time you scheduled to run  High enough to meet demand without burning out the plant 
    OEE (Overall Equipment Effectiveness)  Of the time you scheduled, how productive the equipment actually was  World-class is about 85%. Most plants live around 40% to 60%. 
    TEEP (Total Effective Equipment Performance)  Of all available time, 24 hours a day, every day, what did you actually produce?  Reveals the true ceiling. Big TEEP gaps mean big hidden capacity. 

    Why “hidden factory” is the phrase that matters 

    Here’s the line that should change how you see your plant. If your TEEP is 30%, you have a second factory hidden inside your factory. 

    You’re already paying for the building. You’re paying the depreciation on the equipment. You’re paying most of the labor. That capacity exists; it’s just buried under the 30 losses. And recovering it is almost always far cheaper than building a new line. The 30 losses are the map to that hidden factory, and a typical plant is sitting on a hidden factory worth 30% to 50% of its current capacity. 

    That’s not a rounding error. That’s a second plant you already own. 

    Try it yourself 

    Before the next post, do a back-of-the-envelope estimate for one critical line: 

    • Roughly what percentage of scheduled time does it actually run well? That’s a rough feel for OEE. 
    • Now factor in all the hours it isn’t even scheduled. That gets you toward TEEP. 

    You don’t need precision yet. You’re just trying to feel the size of the gap between what you produce and what you could. That gap is the rest of Part 2. 

    Key takeaways 

    • 30 losses, three families: Equipment (11), Human Efficiency (9), Resources (10). 
    • Loading shows how much you tried; OEE shows how well the equipment ran; TEEP shows the full opportunity. 
    • A typical plant has a hidden factory worth 30% to 50% of its capacity sitting inside its current walls. 
    • You can’t fix what you can’t name. Naming the loss is the first job, and it’s what this part of the series is for. 


    Coming next, Part 2, Post 2: The 11 Equipment Losses. 

  • Business Acumen: Profit vs. Cash, Why They Are Not the Same

    Business Acumen: Profit vs. Cash, Why They Are Not the Same

     Profit vs. Cash, Why They Are Not the Same 

    This is the post most operators and maintainers would skip. Don’t. The day you understand the difference between profit and cash is the day your business cases start getting approved faster. 

    We’ve covered how the business makes money and how to read its three statements. Now comes the idea that quietly decides whether your projects live or die, and almost nobody on the floor is taught it. 

    Profit and cash are not the same thing. They feel like they should be. They are not. Understanding why is one of the most valuable things you can carry into a budget meeting. 

    The simple distinction 

    In plain English. Profit is an accounting concept. It’s what the books say after revenue and expenses are matched up, even if the cash hasn’t actually moved. 

    Cash is the green stuff in the bank. You either have it or you don’t. 

    Here’s the uncomfortable part: a company can post a profit on paper while running out of cash, and a company can be sitting on plenty of cash while losing money. The two numbers tell different stories, and you need to be fluent in both. 

    How they drift apart 

    There are a handful of everyday situations that pull profit and cash in different directions. You’ll recognize all of them. 

    • Inventory builds up. You spent cash buying raw material and converting it, but it’s sitting as work in process or finished goods. That cost parks on the balance sheet as inventory, not in COGS; so profit looks fine, but the cash is gone. 
    • Customers pay slowly. You shipped the product and recorded the revenue and profit, but the cash won’t land for 60 days. Meanwhile, payroll is due Friday. 
    • Big capital projects. You wrote a $2M check for a new line, but only a slice of it gets depreciated this year. Cash is way down; profit barely moved. 
    • Spare parts hoarding. You bought $300K of insurance spares because everyone insisted “we have to have these.” Profit is unchanged. The cash is gone. 

    Why plant leaders should care 

    This isn’t trivia for the finance team. It’s directly about whether your work gets funded. Three reasons: 

    • Capital approvals depend on cash. If the company is cash-tight, your $500K reliability project can get deferred even when the ROI is excellent. The “no” you heard wasn’t about value. It was about cash. 
    • Inventory decisions are cash decisions. Every reduction in excess work in process or dead MRO is cash handed back to the company. That’s a win you can deliver without selling a single extra unit. 
    • “Save money” sometimes means “free up cash,” not “cut expense.” Knowing which one you’re offering changes how you frame the pitch, and changes who says yes. 

    A story your CFO will love 

    Real-world example: the MRO stockroom cleanup. A plant audits its spare-parts stockroom and finds: 

    • $1.2M of MRO inventory on the books. 
    • $340K of it hasn’t moved in five or more years; obsolete or duplicates. 
    • $180K is for equipment no longer even in service. 

    They sell or write off the obsolete parts and tighten the min and max levels on the rest. The result is about $400K of cash returned to the company. The income statement barely flinches, because write-offs actually sting profit in the short term, but the balance sheet and cash position improve in a big way. 

    That is a story the CFO loves, and notice why: it hurt profit slightly while freeing real cash. If you only spoke the language of profit, you’d never pitch it. Because you understand cash, you can. 

    Try it yourself 

    Walk your stockroom, or pull the MRO inventory report. Then: 

    • Find three line items that look like they haven’t moved in years. 
    • Estimate the dollar value sitting on the shelf. 
    • Ask two questions: do we still own the equipment those parts support, and are they still needed? 

    This is a five-minute exercise that routinely surfaces five- and six-figure cash opportunities hiding in plain sight. 

    Key takeaways 

    • Profit and cash are not the same, and a plant leader needs to be fluent in both. 
    • Inventory ties up cash without touching profit until it moves. 
    • Spare parts strategy is a cash strategy. 
    • When a project gets deferred, it’s often a cash issue, not a value issue. Frame it accordingly. 

    Wrapping up Part 1 

    You now have the foundation: how the business makes money, how to read its statements, and why cash and profit tell different stories. That’s “thinking like the business.” From here on, you can look at anything on your floor and ask the only questions that get things funded. What is this doing to cost, to cash, and to risk? 

    Next, we put that lens to work and go hunting. There’s far more money leaking out of your plant than anyone is tracking, and most of it is hiding in places nobody thinks to look. 


    Coming next, Part 2: Where the Money Hides.

  • Business Acumen: Financial Statements for Operators

    Business Acumen: Financial Statements for Operators

    Financial Statements for Operators 

    You don’t need to read them like an accountant. You need to read them like the person who moves the numbers on them. 

    Say the words “financial statements” in a plant and watch people’s eyes glaze over. Don’t let yours. Here’s the good news: there are only three, and you only need a working understanding of each. Together they answer three plain questions. Is the company healthy? Is it growing? Can it pay its bills? 

    Once you can read these three the way you read a downtime report, the budget conversation stops being intimidating and starts being a place where you have the upper hand. 

    The three statements at a glance 

    Statement  What it tells you  Plant floor translation 
    Income Statement  Did we make a profit over a period of time?  Did we ship more value than we burned in costs? 
    Balance Sheet  What do we own and what do we owe right now?  How much inventory and equipment is sitting around? 
    Cash Flow Statement  Did cash actually come in or go out?  Can we pay vendors, payroll, and capital projects this month? 

    The income statement (the P&L) 

    Read it top to bottom and it tells a story: 

    • Revenue. What we sold. 
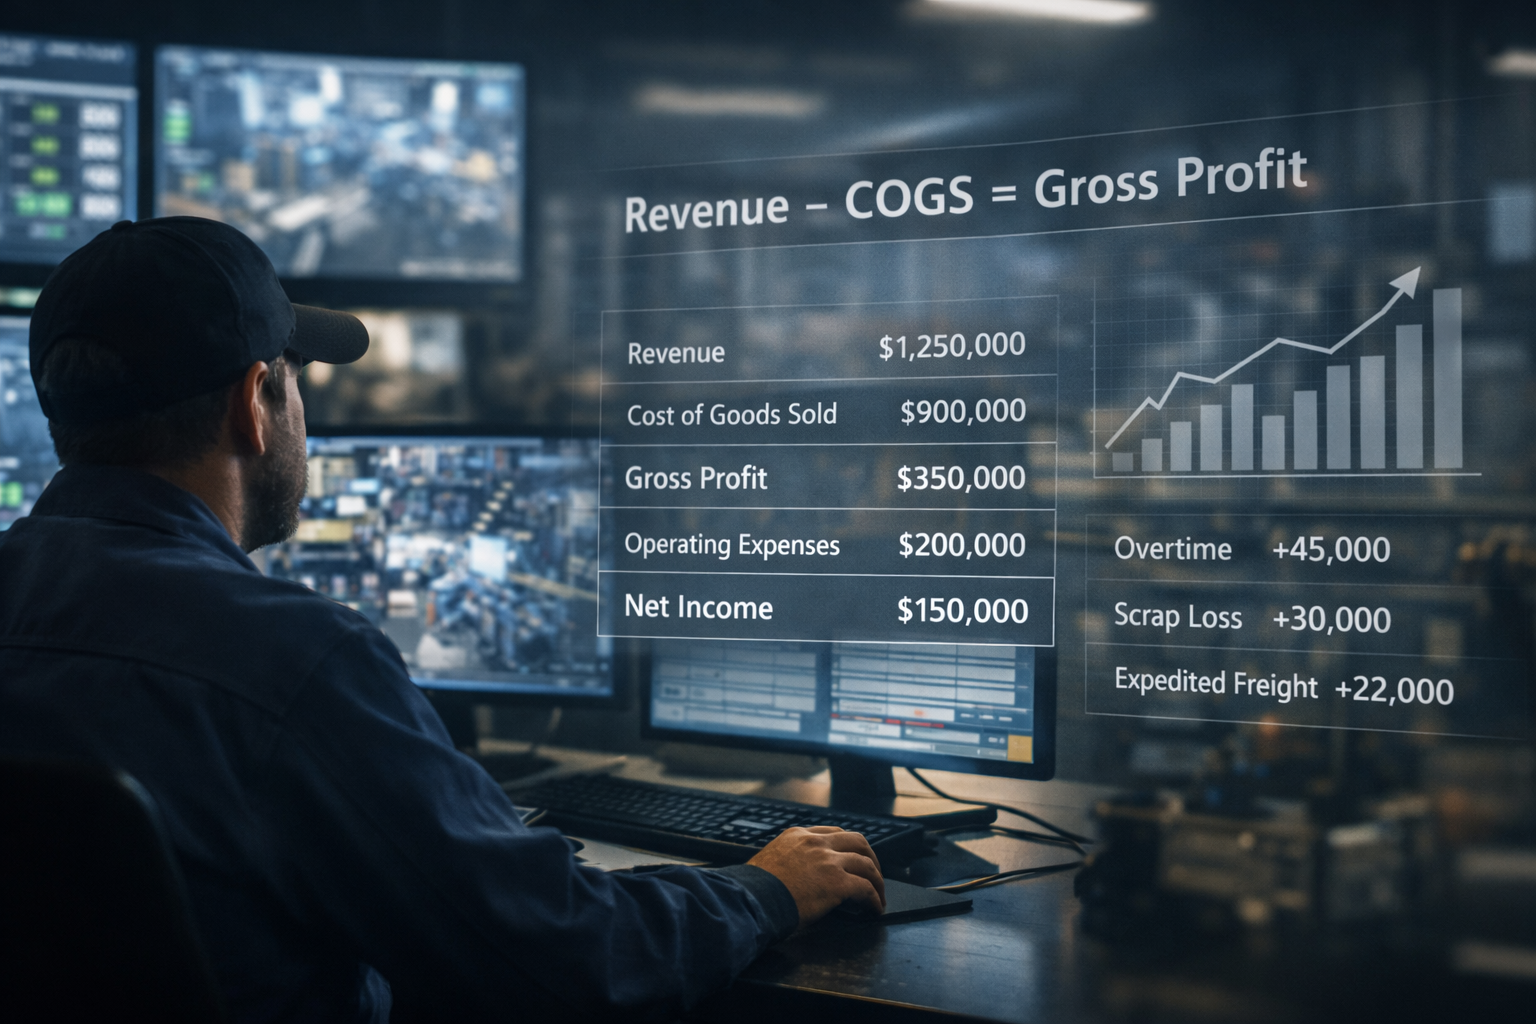
    • Minus Cost of Goods Sold (COGS). What it cost to make what we sold: materials, direct labor, manufacturing overhead. 
    • Equals Gross Profit. 
    • Minus Operating Expenses. Sales, general and administrative, R&D, other overhead. 
    • Equals Operating Income (EBITDA). 
    • Minus Interest, Taxes Depreciation and Amortization. 
    • Equals Net Income. 

    Here’s the part that should make you sit up. Almost everything that happens on your floor lands in one line: COGS. Scrap, rework, breakdown overtime, energy, raw material; all of it flows into Cost of Goods Sold. That is why plant performance is one of the most direct ways to move profit in the entire company. You are not a support function on this statement. You are sitting on the biggest lever it has. 

    Real-world example: how one bad week shows up. A bottling plant strings together breakdowns in week 3 of the month. Watch where it lands on the income statement: 

    • Volume drops, so revenue falls about $180,000. 
    • Overtime to catch up pushes COGS labor up $22,000. 
    • Expedited freight to hit customer dates adds $15,000 to COGS freight. 
    • Scrap from startup defects after each restart adds $9,000 in COGS materials. 

    Total profit hit: roughly $226,000 in one week, and most of it stayed invisible until the month closed. 

    That last line is the whole point. The damage was real on the floor in week 3, but nobody felt it on paper until the books closed weeks later. The person with business acumen connects those two moments before the month ends. 

    The balance sheet 

    If the income statement is a movie of a time period, the balance sheet is a photograph taken on a single day. It shows everything the company owns and everything it owes. 

    Assets = Liabilities + Equity 

    What we have = what we owe + what’s left for the owners. 

    Where does the plant show up here? 

    • Inventory. Raw materials, work in process, and finished goods. Every dollar tied up here is a dollar not earning anything else. 
    • Property, Plant and Equipment. Your machines, lines, and building. Their value is depreciated over time. 
    • Spare parts (MRO). Sometimes counted as inventory, sometimes capitalized. Either way, it’s cash sitting on a shelf. 
    • Accounts Payable. What you owe vendors for materials and services you haven’t paid for yet. 

    Notice the tension built into your stockroom. Carry too much “just in case” spare-parts inventory and you tie up cash that could be working elsewhere. Carry too little and you risk extended downtime when a critical part isn’t on hand. There’s no perfect number; there’s a strategy, and we’ll build it in Part 5. 

    The cash flow statement 

    This is the one that trips people up, so I’ll keep it short here and give it the full treatment in the next post. The headline is this: a company can be profitable and still go broke, because profit and cash are not the same thing. The cash flow statement tracks the actual money moving in and out of the bank account, in three buckets: 

    • Operating cash flow. Cash from running the business. 
    • Investing cash flow. Cash spent on, or received from, buying and selling assets like equipment. 
    • Financing cash flow. Cash from loans, investors, dividends, and debt repayment. 

    Hold that thought. The gap between profit and cash is where a lot of good plant decisions live or die, and it’s exactly where we’re headed next. 

    Try it yourself 

    Pull your plant’s last income statement or ask Finance for one. Find: 

    • Total revenue for the period. 
    • COGS. 
    • Gross profit (revenue minus COGS). 
    • Gross margin percentage (gross profit divided by revenue). 

    Then estimate one thing: what happens to gross margin if your plant cuts unplanned downtime by 5%? Even a rough number is fine. The point isn’t precision yet; it’s building the muscle of connecting a floor action to a financial line. 

    Key takeaways 

    • There are only three statements, and you only need a working grasp of each. 
    • Income Statement is the profit story, and COGS is where your floor lands. 
    • Balance Sheet is what you own and owe; inventory, equipment, and spare parts are your footprint on it. 
    • Cash Flow is actual money movement, and profit and cash are not the same thing. 
    • Plant performance moves COGS directly, and COGS moves net income directly. You hold a real lever. 


    Coming next, Part 1, Post 3: Profit vs. Cash, Why They Are Not the Same.

  • Business Acumen: Thinking Like The Business

    Business Acumen: Thinking Like The Business

    How Your Business Actually Makes Money 

    Before you can fix the floor, you have to see the floor the way the business sees it. 

    Most of us came up through the technical side. We learned the equipment, the process, the schedule. What almost nobody handed us along the way was a simple picture of how the whole company actually makes money. And until you have that picture, every financial conversation feels like it’s happening in a language you were never taught. 

    So let’s start there. Forget the org chart for a minute. No matter how complicated your company looks on paper, it runs on the same simple engine. 

    The engine, in plain English 

    A manufacturing business makes money by converting raw materials into finished goods that customers will pay more for than the materials and the conversion cost combined. 

    That difference is your contribution. You pay your fixed costs out of that contribution, and whatever is left is profit. That’s the whole machine. Everything else in this series is just a more detailed look at one part of it. 

    Three ideas make the engine run: how revenue is built, how costs behave, and what’s left over. Let’s take them in order. 

    The three levers of revenue 

    Revenue doesn’t just show up. It gets built from three knobs, and plant decisions touch all three. 

    • Volume. How many units you ship. 
    • Price. What you charge per unit. 
    • Mix. Which products you ship, because some carry higher margins than others. 

    These interact in ways that aren’t always obvious. Push volume by discounting to move product, and your price knob drops; you might end up flat. Ship more of your high-margin products, and revenue can climb even if total units stay the same. When you free up capacity on a constrained line, you’re not just making “more stuff.” You may be changing the mix, and that can matter more than the raw count. 

    How costs behave: fixed versus variable 

    This is the single most important cost concept on the floor, and it’s the one that explains why downtime hurts the way it does. 

    Cost type  Behavior  Plant examples 
    Fixed  Stays the same whether you make 1 unit or 1,000  Building lease, salaried staff, depreciation on equipment 
    Variable  Rises and falls with how much you produce  Raw materials, packaging, energy on running equipment, hourly overtime 

    Here’s why it matters. When a line goes down, you stop spending the variable cost on the units you didn’t make, except for the labor you are paying to stand around. This raises the cost per unit and the fixed cost meter keeps running the entire time the line sits dark. The lease, the salaries, the depreciation; none of it pauses. That’s why every hour of unplanned downtime costs more than people expect. 

    Contribution margin: the number that sizes everything 

    Contribution margin is the money left from each unit sold after you subtract that unit’s variable cost. It’s what’s available to cover fixed costs and other overhead and then turn into profit. 

    Contribution margin per unit = selling price minus variable cost per unit 

    Total contribution = contribution per unit times units sold 

    Remember the packaging line from the intro? Let’s do the full math this time. 

    Worked example: a pet food packaging line. A 30 lb bag sells for $24. The variable cost (kibble, bag, film, energy, direct labor) is $14. So contribution per bag is $10. 

    Plant fixed costs are $400,000 per month. Divide that by the $10 per bag, and your break-even is 40,000 bags per month. Every bag past 40,000 drops a clean $10 to the bottom line. 

    Now a breakdown costs you 5,000 bags this month. If you were already above break-even, your fixed costs were covered, so that $10 per bag was pure profit. Five thousand bags times $10 is $50,000 of profit gone. Not revenue. Profit. And you’ll never get it back. 

    That’s the move that gets your projects funded. Anyone can say “the line was down for a shift.” The person with business acumen says “that shift cost us $50,000 in profit,” and suddenly the room is paying attention. 

    Break-even thinking 

    Break-even units = fixed costs divided by contribution margin per unit 

    Once you know your break-even point, the picture gets sharp. Every unit above it is profit. Every unit below it is a loss. This is also why a plant running close to break-even feels every disruption so hard; there’s no cushion of profitable volume to absorb the hit. The closer you operate to that line, the more expensive each lost unit becomes. 

    Try it yourself 

    Pick one product line in your plant. Estimate these, or ask Finance: 

    • Selling price per unit. 
    • Variable cost per unit. 
    • Total monthly fixed cost allocated to that line. 

    Then calculate: 

    • Contribution margin per unit (price minus variable cost). 
    • Break-even units per month (fixed cost divided by contribution margin). 
    • How many units above break-even you shipped last month. That’s your profit contribution. 

    If you don’t know these numbers, that’s not a failure. That’s the first finding of the exercise, and it’s exactly the gap this series is here to close. 

    Key takeaways 

    • Revenue is moved by volume, price, and mix, and plant decisions touch all three. 
    • Fixed costs run no matter what you produce. That’s why downtime is so expensive. 
    • Contribution margin is the single most important number for sizing the impact of a loss. 
    • Every unit above break-even is profit. Every unit below it is bleeding.

    Coming next, Part 1, Post 2: Financial Statements for Operators. 


  • Business Acumen for Manufacturers

    Business Acumen for Manufacturers

    The gap nobody warns you about, and the series that closes it 

    In all my years of turning plants from reactive to profit-producing, I’ve found a handful of gaps that show up again and again, and they don’t seem to care what industry you’re in. Food, chemicals, metals, packaging, pulp and paper; the same gaps are waiting in every plant I walk into. 

    The biggest one is leadership constraint. That’s a series for another day. 

    The close second is business acumen, and it’s the one almost nobody sees coming. It’s hidden. Most people don’t know it exists, let alone know they need it. They were promoted because they were good at the technical work. They could fix the line, run the schedule, hit the numbers. Then one day someone in a meeting asked, “Okay, but what does that do to EBITDA?” and the room went quiet. 

    If you’ve ever been in that room, this series is for you. 

    What business acumen actually is 

    Let’s clear something up right away: business acumen is not an accounting class. You don’t need a finance degree, and you don’t need to love spreadsheets. 

    Business acumen is the ability to look at what’s happening on your floor and understand what it’s doing to cost, cash, and risk, and then make decisions accordingly. It’s the bridge between a leaking gearbox and a board meeting. It’s what lets you walk into a budget conversation and say, in language leadership actually funds, “This failure mode is costing us $50,000 a month in lost profit, and here’s the fix that pays for itself in eleven weeks.” 

    That’s the difference between being the person who asks for money and being the person who makes the case for it. 

    Here’s the part that surprises people most: you already have the data. The downtime logs, the work orders, the scrap reports, the parts usage; it’s all sitting in your systems right now. What’s missing isn’t data. What’s missing is the skill to translate that data into the three things every business actually cares about: cost, cash, and risk. 

    That skill is learnable. That’s what this series is about. 

    Why this gap is so expensive 

    When a line goes down, most people instinctively think about lost revenue. But revenue isn’t what disappears. Profit is. 

    Picture a packaging line. A bag of product sells for $24, and the variable cost to make it (materials, film, energy, direct labor) is $14. That leaves $10 of contribution on every bag. Now a breakdown costs you 5,000 bags this month. That’s not $120,000 of revenue gone, and it’s not even the $50,000 of contribution you’d guess at first glance. Once you account for the fixed costs that kept running the whole time the line sat dark, the hit to the bottom line is real money you’ll never get back. 

    The technician who can see that math, and explain it, gets their projects funded. The one who can’t gets told “no budget this quarter” and watches the failure repeat. 

    That’s the cost of the acumen gap. It’s not abstract. It shows up in every deferred repair, every under-resourced reliability program, and every good idea that died because it was pitched in the wrong language. 

    How this series is built 

    We’re going to break business acumen into six parts, with multiple posts under each. We’ll go in order, because the parts build on each other; but each post will stand on its own so you can jump to what you need. 

    Part 1: Thinking Like the Business. Before you can fix the floor, you have to see the floor the way the business sees it. How your company actually makes money, the financial statements that matter, and why profit and cash are not the same thing. 

    Part 2: Where the Money Hides. Money leaks out of a plant in far more places than most people track. We’ll map out exactly where it’s hiding, across equipment, people, and resources, so you stop guessing and start finding it. 

    Part 3: Measuring What Matters. You can’t fund what you can’t size. This is where you learn to measure the bleeding, to put a real number on a loss instead of a gut feeling, and where to focus first. 

    Part 4: Building the Business Case. This is the financial language that gets things funded: cost-benefit analysis, payback, ROI, and the silent killer almost nobody quantifies, the cost of inaction. 

    Part 5: Connecting Reliability to Profit. Here’s where it all comes together at the strategic level: throughput thinking, working capital and spare parts, and how maintenance stops being a cost center and starts being a profit lever. 

    Part 6: Acumen in Action. The capstone. Making decisions and tradeoffs under real constraints, translating technical findings into business language, and putting the whole picture to work in your next staff meeting. 

    A promise before we start 

    Every formula and idea in this series has been kept as simple as it can be while still being honest. If a CFO would scoff at it, it’s not here. If a frontline supervisor wouldn’t understand it, it got rewritten. 

    Simplicity is not the enemy of rigor. It’s the price of being heard. 

    If you can talk about cost, cash, and risk in the same sentence as your equipment, you’re already doing it right. By the end of this series, that won’t feel like a stretch. It’ll feel like how you think. 

    Let’s get to work. 

    Coming next, Part 1, Post 1: How Your Business Actually Makes Money. 

  • Business Acumen for Operations Management

    Business Acumen for Operations Management

    As an operations manager in a manufacturing environment, developing business acumen is essential for aligning operational decisions with broader organizational objectives, enhancing efficiency, and contributing to sustainable growth. Business acumen encompasses the ability to understand and interpret business dynamics, make informed decisions, and drive value creation. In this blog post, I outline the essential building blocks of business acumen that every operations manager in manufacturing should master. These core competencies enable you to seamlessly connect daily operational decisions with the organization’s broader strategic goals, ultimately driving greater efficiency, profitability, and long-term success. 

    1. Financial Literacy

    Understanding financial principles is fundamental, as manufacturing operations often involve significant capital investments, cost controls, and resource allocation. 

    • Financial Statements: Familiarity with balance sheets, income statements, and cash flow statements to assess the company’s financial health, profitability, and liquidity. 
    • Budgeting and Cost Management: Skills in preparing and managing budgets, including variance analysis, fixed vs. variable costs, and techniques like activity-based costing relevant to manufacturing processes. 
    • Key Metrics: Proficiency in metrics such as return on investment (ROI), gross margin, operating expenses, and break-even analysis to evaluate operational efficiency and investment decisions. 
    • Capital Expenditure (CapEx): Knowledge of evaluating and justifying expenditures on equipment, facilities, or technology upgrades. 
    1. Strategic Thinking and Planning

    This involves viewing operations through a strategic lens to support long-term business goals. 

    • Business Strategy Alignment: Understanding how operational activities contribute to the company’s mission, vision, and strategic initiatives, such as market expansion or diversification. 
    • SWOT Analysis: Ability to conduct strengths, weaknesses, opportunities, and threats assessments for your manufacturing unit and the organization as a whole. 
    • Value Chain Analysis: Insight into the end-to-end manufacturing value chain, including supply chain integration, to identify areas for competitive advantage. 
    • Scenario Planning: Techniques for forecasting and preparing for business scenarios, such as economic downturns or supply disruptions. 
    1. Market and Industry Knowledge

    Awareness of external factors ensures operations remain adaptable and responsive to market demands. 

    • Industry Trends: Knowledge of manufacturing-specific trends, such as Industry 4.0 (automation, IoT), sustainability practices, and regulatory changes (e.g., environmental standards or trade policies). 
    • Competitor Analysis: Understanding competitors’ strategies, pricing models, and operational efficiencies to benchmark your performance. 
    • Customer and Supplier Dynamics: Insights into customer needs, market segmentation, and supplier relationships to optimize production planning and inventory management. 
    • Economic Indicators: Awareness of macroeconomic factors like inflation, interest rates, and global supply chain risks that impact manufacturing costs and demand. 
    1. Risk Management and Decision-Making

    Effective business acumen requires anticipating and mitigating risks while making data-driven decisions. 

    • Risk Identification: Skills in assessing operational risks, such as supply chain vulnerabilities, quality issues, or compliance failures, and their potential business impact. 
    • Decision Frameworks: Use of tools like cost-benefit analysis, decision trees, or Pareto analysis to prioritize initiatives in a manufacturing context. 
    • Performance Metrics: Tracking key performance indicators (KPIs) like overall equipment effectiveness (OEE), inventory turnover, and defect rates, linked to business outcomes. 
    • Ethical Considerations: Understanding corporate governance, ethical sourcing, and social responsibility to avoid reputational risks. 
    1. Leadership and Organizational Awareness

    Business acumen extends to leading teams and navigating organizational structures. 

    • Cross-Functional Collaboration: Knowledge of how operations intersect with other departments, such as finance, sales, and R&D, to foster integrated decision-making. 
    • Change Management: Strategies for implementing operational changes while minimizing disruptions. 
    • Talent and Resource Optimization: Insights into human capital management, including workforce planning and skill development, to align with business needs. 

    In conclusion, cultivating strong business acumen as an operations manager in manufacturing extends far beyond technical expertise in production processes. By mastering financial literacy, strategic alignment, market awareness, risk management, and cross-functional leadership, you position yourself to make decisions that not only optimize daily operations but also contribute meaningfully to the organization’s profitability, competitiveness, and long-term sustainability. 

    Investing time in these areas through targeted learning, practical application, and ongoing engagement with industry trends will empower you to transition from managing operations to actively shaping business success. As manufacturing continues to evolve with technological advancements and global challenges, leaders with robust business acumen will be instrumental in driving innovation and resilience. 

    Take the next step today: assess your current strengths, identify gaps, and commit to continuous development. Your enhanced perspective will benefit not only your career but also the broader organization you serve. 

    If you want guidance applying these principles inside your plant, contact our team today at www.reliabilityx.com/contact.

  • Total Cost of Ownership in Maintenance and Reliability Contexts

    Total Cost of Ownership in Maintenance and Reliability Contexts

    Maintenance and reliability professionals increasingly recognize that total cost of ownership (TCO) provides a comprehensive framework for evaluating asset investments. TCO encompasses all costs associated with acquiring, operating, maintaining, and disposing of an asset over its lifecycle, extending beyond the initial purchase price. This approach enables informed decision-making, optimizes resource allocation, and aligns reliability initiatives with organizational financial goals. This blog examines the components of TCO, its calculation, and its application in comparing maintenance strategies. 

    Defining Total Cost of Ownership 

    TCO represents the aggregate financial impact of an asset from acquisition to decommissioning. Industry sources indicate that the initial purchase price often constitutes less than 10-15% of the total, with operating, maintenance, and downtime costs forming the majority, frequently depicted through the “iceberg” analogy, where visible costs (purchase) are minor compared to hidden ones below the surface. 

    Key Components of TCO 

    A thorough TCO analysis includes both direct and indirect costs: 

    • Acquisition Costs: Purchase price, transportation, installation, and initial training. 
    • Operating Costs: Energy consumption, consumables, and daily operational expenses. 
    • Maintenance Costs: Preventive, corrective, and predictive activities, including labor, parts, and service contracts. 
    • Downtime Costs: Lost production, opportunity costs, and emergency response expenses. 
    • Disposal or Residual Costs: Decommissioning, environmental compliance, minus any resale or salvage value. 

    Calculating TCO 

    The standard formula for TCO is: 

    TCO = Acquisition Costs + Operating Costs + Maintenance Costs + Downtime Costs + Disposal Costs − Residual Value 

    For precision over time, costs are often discounted to present value using net present value (NPV) techniques. Maintenance professionals can apply this by tracking historical data on similar assets and forecasting future expenses based on reliability metrics. 

    TCO in Maintenance Strategies: Reactive versus Proactive 

    TCO analysis highlights the financial advantages of proactive approaches. Breakdowns incur high emergency repair and downtime costs, often leading to premature asset replacement. In contrast, precision maintenance (proper bearing installation, torquing, alignment, etc.) minimizes unplanned downtime and optimizes interventions. 

    Studies demonstrate that precision strategies reduce overall costs by 10-40% compared to reactive methods and 8-12% versus purely preventive schedules, through extended asset life and reduced failures. 

    Practical Application for Reliability Professionals 

    To implement TCO effectively: 

    • Collaborate with procurement and finance teams during asset selection to prioritize lifecycle costs over upfront price. 
    • Use reliability data to model scenarios, quantifying downtime impacts (e.g., lost revenue per hour). 
    • Advocate for investments in predictive tools by presenting TCO reductions and ROI projections. 

    By adopting TCO, maintenance leaders can justify budgets, enhance asset performance, and contribute to enterprise profitability. 

    Conclusion 

    Total cost of ownership provides a robust lens for evaluating maintenance decisions, revealing that long-term expenses far exceed initial outlays. Embracing TCO fosters strategic reliability programs that control costs, mitigate risks, and support business objectives. The next blog in this series will address aligning maintenance goals with broader organizational strategies.

    If you are ready to strengthen your maintenance strategy and apply TCO principles with confidence, connect with our team at www.reliabilityx.com/contact

  • Understanding Financial Literacy in Maintenance Contexts 

    Understanding Financial Literacy in Maintenance Contexts 

    As maintenance and reliability professionals, technical expertise in asset management is fundamental to operational success. However, developing financial literacy enables these professionals to demonstrate the broader business value of their work. By understanding key financial statements and quantifying the impact of maintenance decisions, one can align reliability efforts with organizational objectives, justify investments, and contribute to profitability. This blog explores the interpretation of two primary financial statements, balance sheets and income statements, and illustrates how maintenance activities influence costs, revenue, and return on investment (ROI). 

    Key Financial Statements: An Overview 

    Financial statements provide a structured view of an organization’s financial health. For non-finance professionals, focusing on two core statements is essential: 

    • Balance Sheet: This represents a snapshot of the company’s financial position at a specific point in time. It adheres to the equation: Assets = Liabilities + Equity. Assets include resources owned (e.g., equipment, inventory); liabilities are obligations (e.g., debts); and equity reflects owners’ residual interest. In maintenance contexts, fixed assets such as machinery appear here, with their value reduced over time through depreciation. 
    • Income Statement (also known as Profit and Loss Statement): This summarizes revenues, expenses, and profits over a period (e.g., a quarter or year). It shows how much revenue is generated and how expenses deduct from it to yield net income. Maintenance-related costs often appear as operating expenses, directly affecting profitability. 

    These statements interconnect: profits from the income statement flow into equity on the balance sheet. 

    Interpreting the Balance Sheet in Maintenance Contexts 

    The balance sheet highlights asset values and financing structure. For maintenance professionals, property, plant, and equipment (PP&E) is particularly relevant. Routine repairs are expensed immediately, reducing cash without altering asset values significantly. However, major overhauls or improvements that extend asset life or enhance capacity may be capitalized and added to the asset’s book value on the balance sheet and depreciated over time. 

    Effective maintenance preserves or extends PP&E value, preventing rapid depreciation or impairments. Deferred maintenance, conversely, can lead to asset devaluation, weakening the balance sheet and signaling higher future capital needs. 

    Interpreting the Income Statement in Maintenance Contexts 

    The income statement tracks operational performance. Maintenance decisions have a direct bearing here: 

    • Routine repairs and preventive activities are typically recorded as expenses (e.g., under operating or maintenance costs), reducing operating income. 
    • Breakdowns often incur higher emergency repair costs, inflating expenses and lowering net profit. 
    • Proactive strategies, such as precision maintenance, can reduce overall expenses by minimizing unplanned downtime and extending equipment life. 

    High maintenance expenses erode margins, while optimized approaches enhance profitability by controlling costs. 

    The Direct Impact of Maintenance Decisions 

    Maintenance choices ripple through financial statements: 

    • On Costs: Preventive programs lower long-term expenses compared to reactive fixes. Industry insights indicate precision maintenance can reduce costs by 10-40% and unplanned downtime by up to 50%, directly improving income statement results. 
    • On Revenue: Equipment reliability ensures consistent production, preventing revenue losses from downtime. For instance, unplanned outages can halt output, reducing sales and top-line revenue. 
    • On Return on Investment (ROI): ROI measures efficiency, often calculated as (Net Gain from Investment – Cost) / Cost. Maintenance investments (e.g., in condition monitoring tools) yield returns through avoided downtime, extended asset life, and reduced repair costs. Capitalized improvements increase asset base but spread costs via depreciation, potentially improving ROI over time. 

    Examples from practice include manufacturers achieving annual savings of millions through predictive maintenance, with ROI realized quickly via lower expenses and sustained revenue. 


    Practical Application for Maintenance Professionals 

    To leverage financial literacy: 

    • Track how maintenance budgets affect departmental expenses on the income statement. 
    • Quantify downtime costs (e.g., lost production value) to justify preventive investments. 
    • Collaborate with finance teams to model ROI for reliability initiatives, using metrics like total cost of ownership. 

    By articulating these impacts, maintenance leaders can secure resources and elevate their strategic role. 

    Conclusion 

    Financial literacy empowers maintenance and reliability professionals to translate technical decisions into business language. Mastering balance sheets and income statements reveals how reliability efforts drive cost control, revenue protection, and superior ROI. This alignment not only enhances asset performance but also supports organizational sustainability and growth. Future blogs in this series will explore related topics, such as cost-benefit analysis for reliability strategies.